
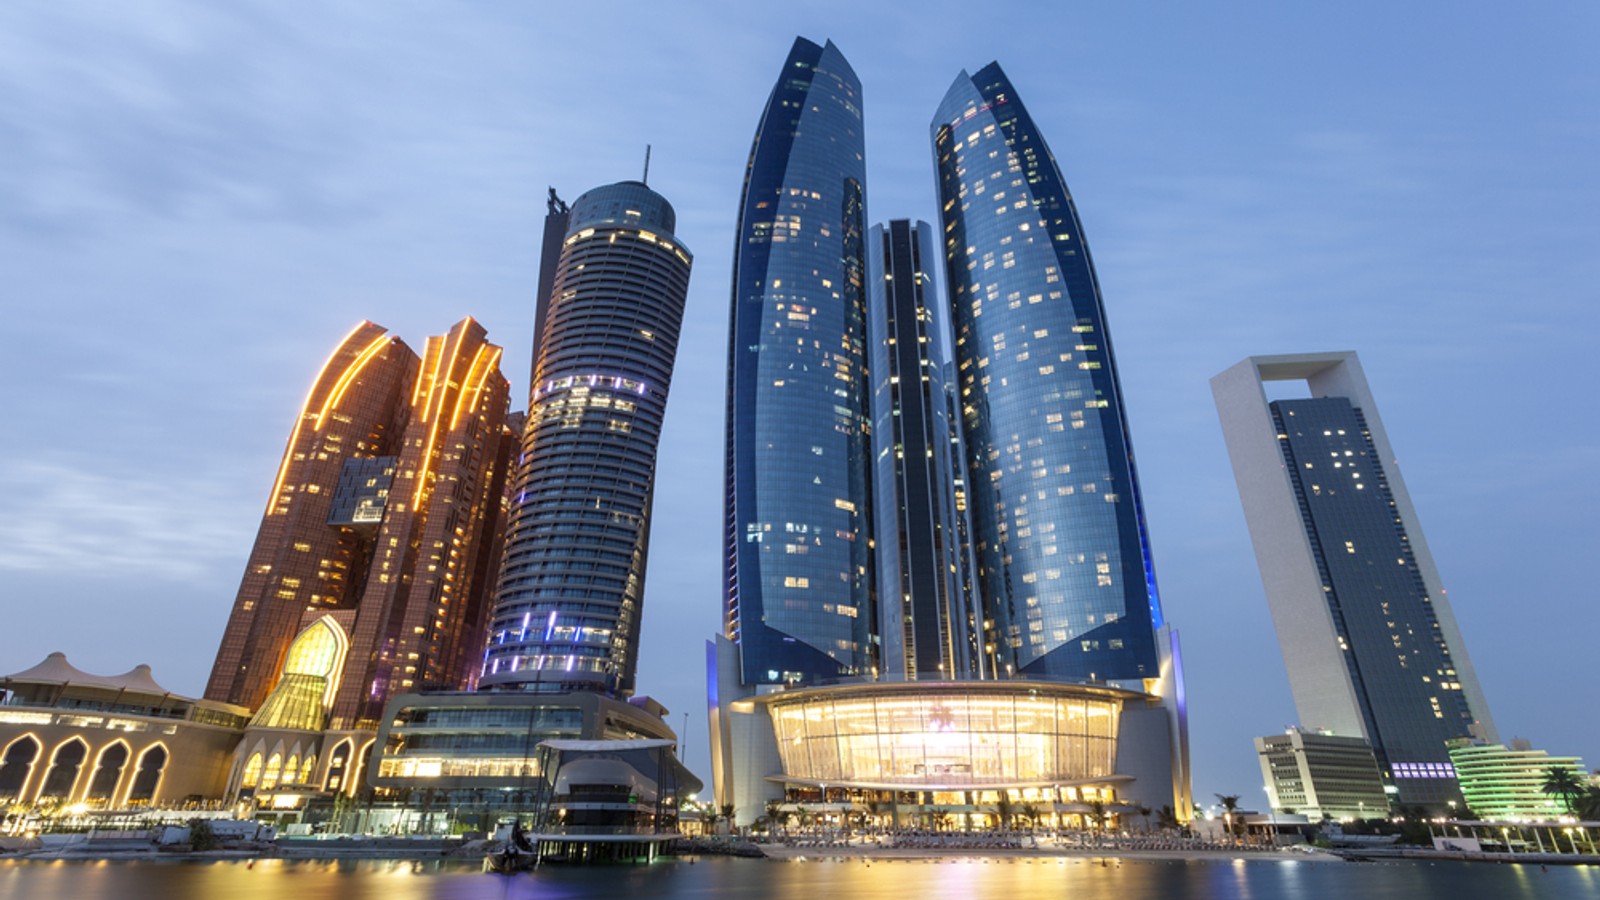
Aldar and Abu Dhabi Commercial Bank have completed the first mortgage registration on an off-plan property under a new framework from the Abu Dhabi Real Estate Centre. It opens an earlier financing route for eligible buyers, with several questions still worth asking before relying on it.
Abu Dhabi Registers Its First Off-Plan Mortgage, Letting Buyers Who Have Paid 50% Borrow Before Handover
Aldar and Abu Dhabi Commercial Bank have completed the first mortgage registration on an off-plan property under a new framework from the Abu Dhabi Real Estate Centre. It opens an earlier financing route for eligible buyers, with several questions still worth asking before relying on it.
Why This Matters
Abu Dhabi's market is increasingly built on off-plan sales, and until now buyers who wanted a mortgage generally had to wait close to completion. A bank can now be recorded against an unfinished unit, which gives buyers a way to arrange financing earlier and gives lenders a formal legal position. It is a structural change to how off-plan purchases can be funded, not just a new product.
What Changes for an Eligible Buyer
From Registration to Handover
Buyer Reaches 50%
The buyer has paid at least half of an eligible unit's value to the developer.
Mortgage Interest Recorded
The mortgage interest is entered in the Initial Real Estate Register, creating a formal record for buyer, developer and lender.
Bank Named Before Handover
The financing bank can appear on the mortgage registration certificate before the property is handed over.
Bank Funds the Balance
The lender can fund the remaining instalments during construction and the final payment at handover.
What 50% Looks Like on a Real Price
Regulator, Developer and Banks
Abu Dhabi Real Estate Centre
Launched the framework and enables mortgage interests to be recorded in the Initial Real Estate Register.
Aldar Properties
Completed the first registration, with its financial chief calling it a step towards greater transparency and accessibility.
Abu Dhabi Commercial Bank
The bank on the first registered mortgage under the framework.
The developer says its in-house mortgage advisory service gives free access to options from more than six conventional and Islamic banks. Lenders it lists are:
What It Means, and What Is Still Open
Less Cash Tied Up During Construction
Being able to finance later instalments could ease the strain of funding a multi-year payment plan from savings, and may give earlier certainty over borrowing costs, depending on the product chosen.
A Formal Interest Before Completion
Recording the bank in the register gives lenders a clearer legal position, which can strengthen protections if a dispute arises and may encourage more banks to participate.
It Fits an Off-Plan-Led Market
Off-plan deals made up about 89% of residential sales value in Abu Dhabi in the first half of 2026, and developers rely on pre-completion sales to fund construction. A smoother financing route supports that model.
Dubai Is Moving the Same Way
Recent reports describe a major Dubai developer and a large bank offering early financing options before handover, suggesting UAE off-plan financing is shifting earlier across the market.
The Framework Is Live, Uptake Is Unproven
One completed registration shows the process works. How many developers, banks and units participate will determine how widely buyers can actually use it.
Not Every Project or Buyer Qualifies
The route applies to eligible units and participating institutions meeting requirements, and only to buyers who have paid at least 50%. Buyers below that point cannot use it yet.
Repayment Timing and Pricing Are Open Questions
The announcement does not say when repayments begin, how interest is charged while the loan is drawn during construction, or whether rates can be fixed early. Buyers should get these in writing from the bank.
A Mortgage Does Not Remove Construction Risk
Borrowing earlier does not change delivery risk. Buyers still depend on the developer completing the project, so track construction progress and the handover date regardless of financing.
Questions for Your Bank Before Using This Route
- Is my unit and developer part of the framework, and is your bank a participating lender?
- What maximum amount can you lend against the outstanding balance, and what income checks apply?
- When do repayments start, and how is interest charged while funds are drawn during construction?
- Can I fix the rate now, and what are the fees, early settlement terms and valuation requirements?
- What happens if handover is delayed, and how does that affect my loan?
Registering a bank's interest on an unfinished home is a meaningful step for Abu Dhabi's off-plan market, and it brings earlier financing within reach of buyers who have paid half the price. The framework is real, but the experience of using it will depend on which projects and banks take part, and on the terms they offer. For now, the sensible approach is to treat it as an option to price and compare, not a default.
About the author
Sahr Kamal
Associate Director
One of the UAE’s most experienced and trusted real estate professionals, Sahar Kamal brings over 20 years of deep market expertise, a remarkable track record of closing more than $1.5 billion in property transactions, and multiple awards from some of the region’s leading developers.
About the author
Sahr Kamal
·Associate DirectorOne of the UAE’s most experienced and trusted real estate professionals, Sahar Kamal brings over 20 years of deep market expertise, a remarkable track record of closing more than $1.5 billion in property transactions, and multiple awards from some of the region’s leading developers.


