
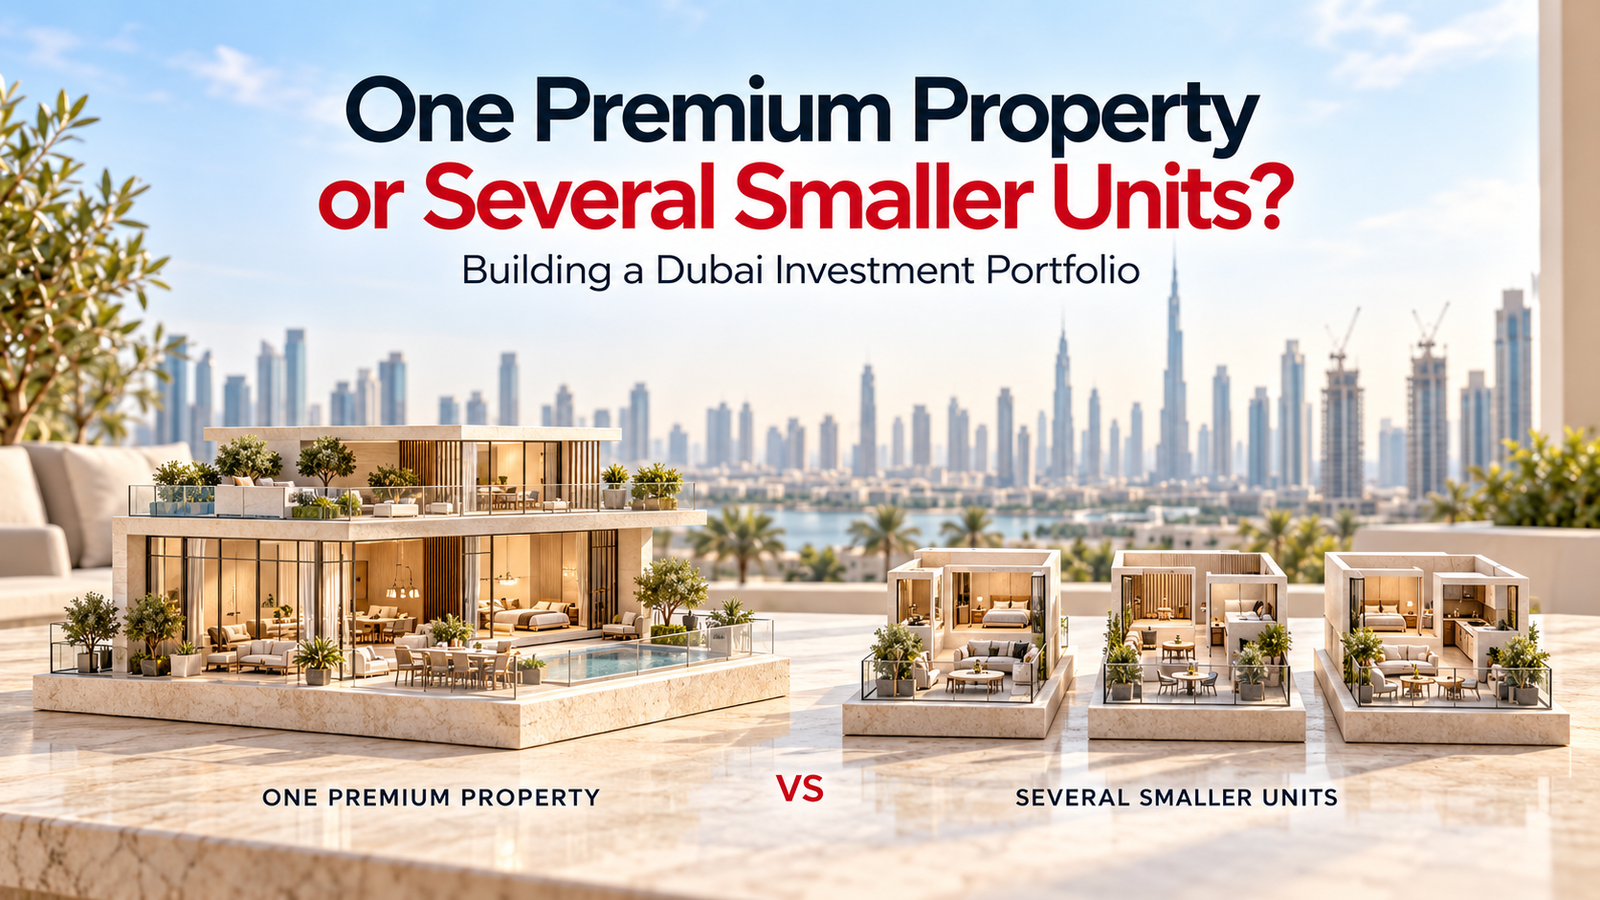
Compare one premium property with several smaller Dubai units through a practical case study covering capital allocation, concentration risk, costs, management and resale flexibility.
A larger budget creates a choice: commit to one premium home, or divide the same purchase allocation among several smaller units. For a Dubai property investment portfolio, the useful comparison is how each structure affects your commitments, exposure and future selling options.
The answer depends on the individual properties, your funding capacity and your intended exit. This guide starts with an illustrative case, then tests the practical trade-offs without assuming either strategy produces a higher return.
Assume cash purchases with the same combined property price. Acquisition costs, financing and reserves are excluded from these prices and must be budgeted separately. The example does not describe available listings.
1. Compare the commitments behind the headline price
Equal property prices do not guarantee equal cash requirements. List the fees, near-term payments and reserve needed for each option. If one strategy uses debt, compare borrowing costs and repayment obligations on a consistent basis rather than treating leveraged and cash purchases as equivalent.
- Acquisition: record the agreed allocation of registration charges, brokerage and other completion costs.
- Holding: include service charges, insurance, maintenance and financing where applicable.
- Off-plan: map every instalment, including payments that could fall due before resale is possible.
- Reserves: retain capacity for delays, unexpected expenses and a longer ownership period.

2. Distinguish more units from broader diversification
One property concentrates the investment in that asset. Several properties may spread some unit-specific exposure, but the benefit depends on what actually differs between them. Three apartments in the same tower can share the same construction timetable, surrounding supply and target buyer.
The following is a property-specific application of diversification principles, rather than a claim that a particular mix will prevent losses:
- Check exposure to the same developer and project.
- Review overlapping handover dates and major payment deadlines.
- Compare communities, property types and likely buyer budgets.
- Consider existing property holdings alongside the proposed purchases.
- Remember that different Dubai addresses can still share citywide market risks.
If all three units are in one delayed project, all three can be affected. If one of three equally priced units is in a separate affected project, one-third of the original property-price allocation has direct exposure to that project. This arithmetic does not measure the eventual loss or remove wider market risk.
3. Separate percentage-based costs from repeated charges
Some charges scale with transaction value, while others repeat for each qualifying transaction. DLD’s Property Sale Registration service, reviewed on 29 October 2026, lists a service-partner fee of AED 4,000 plus VAT for a sale valued at AED 500,000 or more through that service.
| Assumption | One AED 4.8M sale | Three AED 1.6M sales |
|---|---|---|
| Separate qualifying completed-sale transactions | 1 | 3 |
| Listed service-partner fee before VAT | AED 4,000 | AED 12,000 |
| What the figures exclude | Registration charges and all other costs | Registration charges and all other costs |
This assumes separate completed sales through the same listed trustee service, with no special adjustment. Different channels or transaction structures can have different charges. Obtain transaction-specific quotations; do not apply this example automatically to off-plan bookings or treat it as an all-in buying-cost estimate.
At equal total purchase value, a charge calculated at the same percentage would produce the same combined amount. Repeated fixed charges, inspections, financing arrangements and later sales can make the actual totals different.
4. Assess the work involved during ownership
One premium property means one unit to monitor, but it may have specialised maintenance or a more expensive service package. Several smaller properties create more individual records, inspections and decisions. Neither structure is automatically cheaper to manage.
- Before handover: track developer updates, instalments and transfer eligibility for each contract.
- At completion: organise inspections, defect follow-up, handover and account setup.
- During a hold: monitor charges, maintenance and property-management arrangements.
- Before selling: review comparable transactions, documents and marketing for each unit.
For overseas investors, define who will handle local tasks and request a written service scope and fee quotation. Delegation can reduce the workload you personally carry, while adding a cost that belongs in the investment calculation.
5. Evaluate partial-sale flexibility and actual liquidity
With separate units, you can potentially offer one for sale while retaining the others. With a single property, a conventional sale usually means disposing of the whole asset. That difference can matter if you expect to release part of your capital at a later date.
However, the option to list a smaller unit is not a promise of a quick sale. Achievable price, buyer funding, competing listings, contractual restrictions and transaction costs determine how much cash is released and when.
| Decision point | One premium property | Several smaller units |
|---|---|---|
| Capital release | Would selling the whole asset fit your plans? | Would a partial exit help, after costs and any debt settlement? |
| Future buyer | What evidence supports demand at this price bracket? | What evidence supports each unit’s specific buyer proposition? |
| Off-plan restrictions | When can this contract be transferred? | Could restrictions or instalments affect several units together? |
| Pricing | How distinctive is the home relative to alternatives? | Could your units compete with each other or developer inventory? |
6. Choose a portfolio structure you can support
One premium home may suit an investor who values a particular property, accepts concentrated exposure and has no immediate need for partial disposals. Several smaller units may suit an investor who values separate exit choices and can support the additional commitments. These are decision criteria, not recommendations based only on unit count.
What is the total cash required? Where is exposure concentrated? Which payments overlap? Who manages the homes? What evidence supports the next buyer’s budget? What happens if every planned resale takes longer?
For investors buying off-plan to resell, test the portfolio as a set of contracts and cash deadlines. Three individually appealing purchases can become difficult to hold if large instalments fall due together. A workable structure should remain fundable even when the intended exit is delayed.
Frequently asked questions
Is one expensive property better than several smaller properties in Dubai?
There is no universal winner. Compare the individual assets, entry prices, total commitments, concentration and ability to hold them. Unit count does not establish expected profit.
Do three properties automatically diversify my investment?
No. Properties can share the same developer, project, buyer segment and market exposure. Review what differs and what remains concentrated across the holdings.
Are smaller units always easier to sell?
No. They allow separate sales, but liquidity depends on actual demand, price, condition, competing supply and transfer requirements. A smaller ticket alone does not guarantee a buyer.
Should the whole budget go into property prices?
Budget separately for applicable acquisition charges, ownership commitments and reserves. If borrowing or buying off-plan, account for the payment schedule and the possibility of a longer hold.
Build your Dubai property investment portfolio with M R One Properties
M R One Properties helps investors compare individual opportunities alongside portfolio commitments and resale objectives. Its published recognition includes No. 1 at Emaar’s H1 Broker Awards 2026, No. 5 at Emaar’s Annual Broker Awards 2025 and No. 7 at DAMAC’s Annual Broker Awards 2025—a Top 5 Emaar and Top 10 DAMAC finish for those annual award periods.
Discuss the properties, payment schedules and exit choices behind your next allocation with our team.
Compare your portfolio options
About the author
Jaber Ishaq
International Sales Director (GCC)
With vast experience in Dubai real estate and over 15 years with leading GCC national banks, Jaber Isaq brings a rare blend of market insight, financial expertise, and investor trust, helping clients make smarter property decisions with confidence.
About the author
Jaber Ishaq
International Sales Director (GCC)With vast experience in Dubai real estate and over 15 years with leading GCC national banks, Jaber Isaq brings a rare blend of market insight, financial expertise, and investor trust, helping clients make smarter property decisions with confidence.


